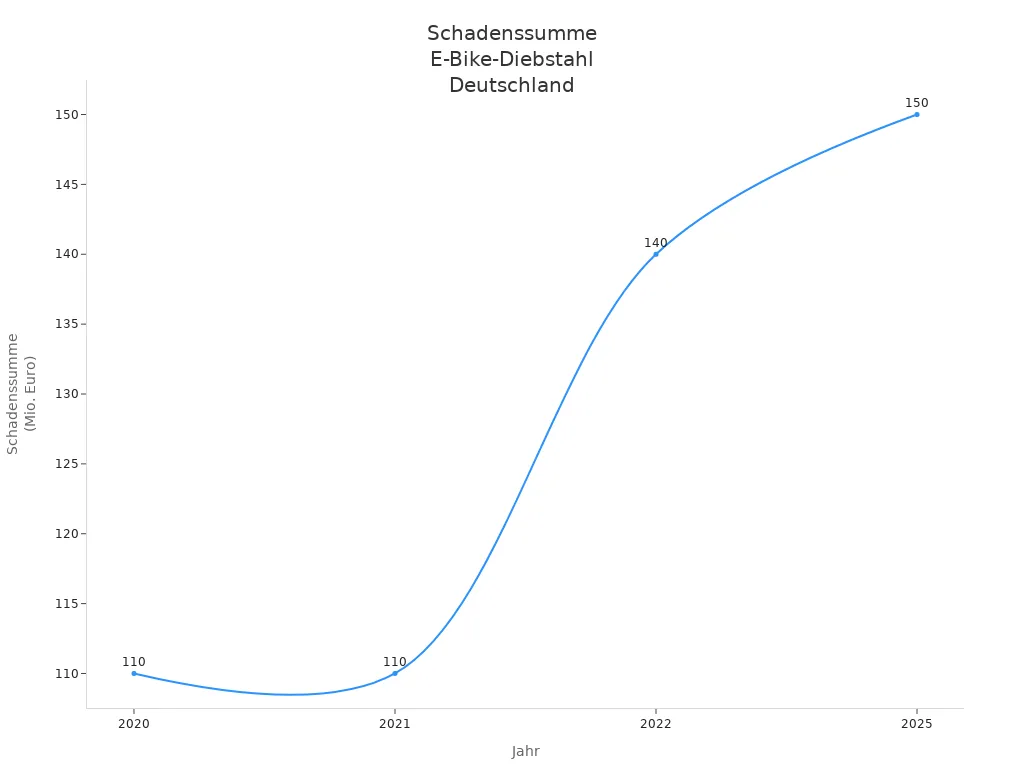
You protect your e-bike not only against theft but also against high costs in the event of damage. Every year in Germany, theft and damage claims total up to 140 million euros. Especially expensive models are often affected. The following chart shows how sharply the total claims have risen in recent years:
Wondering which services an insurance policy covers, when it makes sense, and how much the premiums cost? You will find clear answers here.
Key Findings
E-bike insurance protects against theft, vandalism, and accident damage. It also covers electronic damage and wear and tear.
Home contents insurance often only offers limited protection. It usually only applies to theft from locked rooms.
Separate e-bike insurance makes sense for valuable or frequently used e-bikes. It protects against high financial losses.
The cost of e-bike insurance depends on the value of the bike and the desired coverage. Annual premiums range between 50 and 200 euros.
In the event of a claim, you report the damage directly to the insurance company. Processing is usually fast and straightforward.
E-Bike Insurance: Services and Coverage
What is covered?
E-bike insurance protects you against many risks that can occur in everyday life. You get protection not only against theft but also against other types of damage. The most important services are listed here:
Theft: The insurance pays out if your e-bike is stolen – whether from a cellar, the street, or a garage.
Vandalism: You are covered if someone intentionally damages your e-bike.
Accident and crash damage: Following a fall or accident, the insurance covers the repair costs.
Electronic damage: Damage to the battery, motor, or display is often included.
Wear and tear: Many plans cover the costs of worn-out parts, such as brakes or chains.
Protection for accessories: Permanently mounted accessories, such as a built-in lock or luggage rack, are often included.
Tip: Most e-bike insurance policies also offer protection against fire, explosion, lightning, and natural hazards. Vandalism cases are rare, but you are covered in an emergency.
Many providers offer different plans. You can choose between basic and premium protection. A basic plan usually covers theft and vandalism. A premium plan additionally protects against accident damage, electronic damage, and wear and tear.
The following table shows which services are included in most e-bike insurance policies in Germany:
Service |
Description |
|---|---|
E-Bike Liability |
Covers damages you cause to others. |
Includes liability and partial comprehensive coverage, also protects your own e-bike. |
|
Partial Comprehensive Insurance |
Insures against damage from fire, explosion, short circuits, falls after animal collisions, and storm damage. |
Coverage for animal bite damage |
Protects against damage caused by animals biting cables and lines. |
Sum insured |
Often up to €100 million for personal injury, property damage, and financial loss. |
Differences from home contents insurance
Many think that their home contents insurance is enough for their e-bike. This is only partially true. The differences are important so you know when a special e-bike insurance policy makes sense.
Insurance Type |
Insurance Coverage |
|---|---|
Home Contents Insurance |
Protects e-bikes only in case of burglary from a closed room, such as a cellar or garage. |
Offers protection against theft, vandalism, battery, and electronic damage, even outside the home. |
Aspect |
E-Bike Insurance |
Home Contents Insurance |
|---|---|---|
Comprehensive protection, even when on the go |
Protection usually only at the insured location |
|
Coverage of attachments |
Yes |
No |
Coverage of total value |
Full value of the e-bike |
Only a portion of the total value |
Night-time clause |
Usually non-existent |
Often present, protection limited at night |
Comprehensive insurance |
Mandatory for fast e-bikes |
Not necessary |
Insurance costs |
Similar or slightly higher |
Cheaper, but less protection |
Home contents insurance often only protects your e-bike if it is stolen from a locked room.
Damage caused by wear and tear, electronics, or individual parts like the battery and saddle is usually not covered.
Many home contents insurance policies have a night-time clause. This means your e-bike is often not insured at night between 10 p.m. and 6 a.m.
E-bike insurance offers you more comprehensive protection. It is also valid when on the go and covers more types of damage.
Note: For fast e-bikes with speeds exceeding 25 km/h, you need a separate comprehensive insurance policy. Home contents insurance is not sufficient here.
With a special e-bike insurance policy, you are much better protected. You can use your e-bike worry-free – regardless of whether you ride it daily or only use it occasionally.
E-Bike Insurance: Necessity and Purpose
When is home contents insurance enough?
Are you wondering if your home contents insurance is enough for your e-bike? The answer depends on several conditions. Home contents insurance usually only protects your e-bike in the event of theft from a closed room, such as a cellar or garage. You can extend the protection with an additional "bicycle theft" module. The sum insured is based on the total sum insured of your home contents insurance.
Condition |
Description |
|---|---|
Theft coverage |
E-bikes are covered if they are located in closed rooms, e.g., in the cellar. |
Additional modules |
With the 'bicycle theft' module, protection can be extended to theft outside of closed rooms. |
Sum insured |
The sum insured for e-bikes depends on the total sum insured of the home contents insurance. |
You should be aware that e-bikes are often covered for only 1-5% of the total sum insured. The protection only applies in the event of burglary or fire within the apartment or cellar. You must clarify damages from theft on the open street individually with your insurer.
Tip: Keep the purchase receipts for your e-bike and the lock. This makes it easier to assert claims in the event of damage.
Check whether there is a night-time clause. This can restrict theft protection at night. Also, verify whether the insurance reimburses the replacement value or only the current market value.
For whom does separate insurance make sense?
Separate e-bike insurance is particularly recommended for certain user groups:
You own a valuable e-bike. The material loss in the event of theft or total loss can be very high.
You use your e-bike regularly. The risk of falls and accidents increases with usage.
You do not have home contents insurance. A standalone policy still offers you protection.
E-bike insurance pays off if your electric bike costs more than 500 euros. Many entry-level e-bikes often cost 2,000 euros or more. In this case, separate insurance protects you against high financial losses.
Note: E-bike insurance is not legally mandatory. You can decide for yourself whether you want to provide additional coverage for your e-bike. Protection is especially sensible for expensive models and frequently used e-bikes.
Costs and Purchasing
Premium factors
Many factors determine how much you pay for your insurance. The most important point is the value of your e-bike. The more expensive the bike, the higher the premium. Age and condition also play a role. A new bike often costs less to insure than a used one because its condition is better. Your place of residence also influences the premium. In the city, you usually pay more because the risk of theft and accidents is higher than in rural areas.
Here is an overview of the annual costs:
E-Bike Price Range |
Annual Costs |
|---|---|
Up to 2,000 euros |
50 to 80 euros |
2,000 to 4,000 euros |
80 to 150 euros |
Over 4,000 euros |
150 to over 200 euros |
The scope of protection also influences the price. If you want to insure accident damage, wear and tear, and accessories, you will pay more. Many insurers offer inexpensive plans starting at 70 euros per year. For a bike worth 2,500 euros, the costs are usually 60 to 70 euros annually.
Tip: Many insurance companies require a certified lock with a VdS or ADFC seal. Always lock your bike to a fixed object.
Required Documents
You need some documents to take out insurance. This ensures that your bike is properly protected in the event of damage:
Purchase contract or invoice as proof of the purchase price.
Frame number for clear identification.
Photos of the bike to document its condition.
Details regarding the lock, often with proof of the VdS or ADFC seal.
Your personal details such as name, address, and date of birth.
Bank details for premium payments.
Note: Keep all documents handy. This makes the process fast and straightforward.
Claims Settlement and Additional Services
Procedure in the event of damage
If damage occurs, report it directly to your insurance company. Processing is usually straightforward. Many customers report that the settlement process works quickly and simply. You submit specific evidence so that the insurer can verify the damage. This includes:
The bicycle invoice with address and frame number
Purchase receipts for attachments and the lock
A completed claim form with details of the location, time, and sequence of events
Photos of the damage or the bicycle
The police report in written form
The insurance certificate
The processing time depends on the type of damage. Theft claims are often processed in 5 to 17 working days. Repair claims usually take 3 to 7 days for approval, followed by the repair. Complicated cases can take up to two months. Generally, you will receive feedback and reimbursement after about a month, provided all documents are complete.
Type of damage |
Timeframe |
|---|---|
Theft with documentation |
5-17 working days |
Repair damages |
3-7 days (approval) + repair |
Complicated cases |
up to 2 months |
Special rules apply to pedelecs and S-pedelecs. For S-pedelecs, you need motor vehicle liability insurance. For regular pedelecs, private liability insurance is often sufficient. Conventional bicycles do not require special insurance.
Additional options
Many insurance companies offer additional services. These protect you from further risks and make the insurance cover more flexible.
Additional service |
Description |
|---|---|
Protection for the entire bicycle and individual parts such as the battery and wheels. |
|
Accident protection |
Coverage for damages caused by accidents or breakdowns. |
Vandalism |
Insurance against malicious destruction. |
Flood protection |
Coverage for damages caused by flooding. |
Moisture damage |
Insurance for damage to the battery, motor, or control system due to moisture. |
Breakdown service |
Assistance with defects during use, similar to a car. |
Special services for batteries |
Comprehensive protection for batteries, including theft and defects. |
The additional options vary depending on the provider. Some insurance policies exclude older or used bicycles. The purchase price and the type of lock play a role. You can often insure individual parts more cheaply, but the protection then only applies to those parts. The notice period is usually 1 to 3 months.
Criterion |
Notes |
|---|---|
Age |
Best to insure immediately after purchase. Older models are often excluded. |
Purchase price |
There are price limits for insurance coverage. |
Individual parts |
Individual parts can be insured more cheaply. |
Lock |
The type of lock is specified. Proof required. |
Total loss |
Reimbursement at replacement value or current value; observe waiting periods. |
Notice period |
1 – 3 months, written notice required. |
Exclusion criteria |
Used bicycles are often uninsurable. |
Tip: Check the terms and conditions of your provider carefully so you know which additional services apply to your bicycle.
You should adapt your e-bike insurance to your needs. Experts recommend comparing different offers and paying attention to important criteria:
Protection against vandalism and accident damage
Coverage for battery and electronic defects
Type of lock and term of the insurance
Option for a breakdown service
Check the insurance terms carefully. Consider discounts, for example for ADAC members. Ask yourself whether you could afford the financial loss and how important the e-bike is to you.
FAQ
How much does e-bike insurance cost?
Costs depend on the value of your e-bike, its age, and the desired level of protection. You usually pay between 50 and 200 euros per year. An expensive e-bike costs more in premiums.
What does e-bike insurance cover?
You receive protection against theft, vandalism, accident damage, and electronic defects. Many insurance companies also cover repairs for wear and tear and damage to the battery.
What happens in the event of a claim?
You report the damage directly to your insurance company. You submit the necessary documents. Processing usually takes a few days. You will receive feedback and the reimbursement.
What is the difference between e-bike and pedelec insurance?
An e-bike travels faster than a pedelec. For e-bikes over 25 km/h, you need motor vehicle liability insurance. For pedelecs, private liability or special bicycle insurance is often enough.