Even if your budget is limited, you can afford an e-bike in installments. Flexible payment models allow you to get started with monthly payments as low as 10 or 20 euros. Many retailers offer fast and uncomplicated processing for buying an e-bike in installments. In 2020, the share of installment payments in the bicycle trade was 2.25 percent of total turnover. One example shows that at some specialist dealers, as much as 10 percent of online purchases are handled via installment payments for e-bikes. More and more people are using this option because they can start riding immediately without having to save up for a long time.
Key takeaways
Buying an e-bike in installments means paying the price in monthly amounts and using the bike immediately.
Flexible terms and installment amounts adapt to your budget and allow for financial freedom.
Pay attention to interest rates and contract terms to avoid unexpected costs and long-term commitments.
Different financing models such as retailer installment plans, bank loans, leasing, or subscriptions offer various advantages.
Compare offers carefully and use subsidy programs to get the best e-bike at a fair price.
E-bike in installments
What does installment purchasing mean?
When buying an e-bike in installments, you do not pay the purchase price all at once, but in fixed monthly amounts. Many retailers offer you flexible terms between 6 and 60 months. You can often start with as little as 10 or 20 euros per month. The monthly installment depends on the price of the e-bike and the selected term. The longer the term, the lower the installment. In return, you usually pay slightly more interest in total.
Tip: Many retailers offer 0% financing for short terms. This allows you to buy an e-bike in installments without paying additional interest costs.
To take out an installment plan, you must meet a few requirements:
You are a resident of Germany.
You have permanent employment and are no longer in your probationary period.
You have no negative SCHUFA entries.
You can provide proof of regular income or collateral.
Process and conditions
The process for an e-bike in installments is simple and fast. You select your desired bike from the retailer and fill out an installment form. This is often done directly online. The retailer then checks your creditworthiness. If everything is in order, you sign the contract and have the e-bike delivered.
You fill out the financing form.
The retailer checks your credit rating.
You sign the contract.
You receive your e-bike.
The decision regarding the installment purchase is usually made in real-time. You do not need to send documents by post. The first installment is debited no earlier than 30 days after delivery. Many retailers offer you flexible repayment options, such as extraordinary repayments or adjustments to the installment amount in the customer portal.
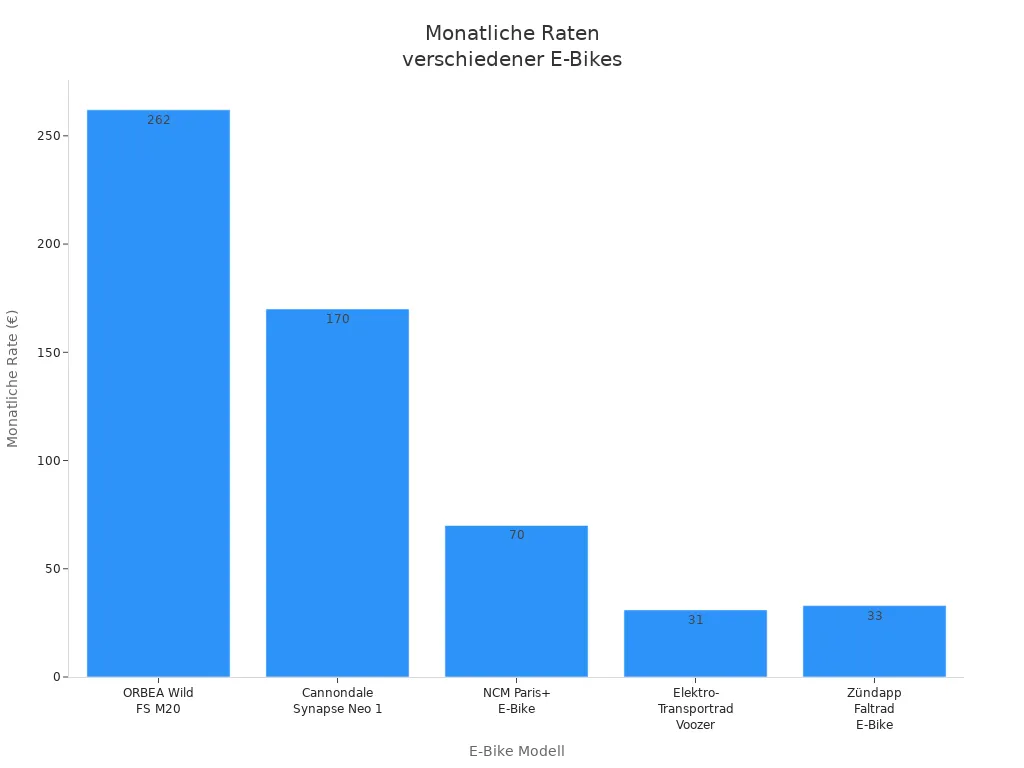
Here you can see typical examples of monthly installments with a 24-month term and about 4.7% interest:
Model (Example) |
Purchase price (€) |
Monthly installment (€) |
|---|---|---|
ORBEA Wild FS M20 |
6,000 |
approx. 262 |
Cannondale Synapse Neo 1 |
3,900 |
approx. 170 |
NCM Paris+ E-Bike |
1,600 |
approx. 70 |
Electric cargo bike Voozer |
700 |
approx. 31 |
Zündapp folding e-bike |
750 |
approx. 33 |
With an e-bike in installments, you can ride off immediately and distribute the costs comfortably. The processing is fast, uncomplicated, and often completely digital.
Advantages
Financial flexibility
Would you like an e-bike, but don't have a large budget? With an e-bike in installments, you can still fulfill your wish. The monthly installments adapt to your wallet. Many providers allow you to choose a term between 6 and 60 months. This way, you decide for yourself how high your monthly burden is.
Tip: Many retailers offer 0% financing. This means you pay no interest if you pay off the e-bike within a certain time. This model is very popular in Germany in particular. You can often pay for 10 to 30 months without interest. However, be aware that not every model is available for 0% financing.
Immediate use
You don't have to wait until you have paid for the e-bike in full. Once the installment purchase is concluded, the bike is yours and you can start riding immediately. Many users report that they use their new e-bike right after signing the contract. This immediately brings you more mobility and riding fun. You benefit directly from all the advantages, even if you spread the costs over many months.
Note: By paying in installments, you can often afford a better equipped or higher quality model that might be too expensive as a one-time payment.
Individual installment amount
With many providers, you can flexibly adjust the amount of your monthly installment. You decide how much you want to pay per month. This helps you keep an eye on costs and avoid overextending yourself.
Here you can see how flexible the installment amount is with various providers:
Provider |
Term (months) |
Minimum installment |
Features |
|---|---|---|---|
Santander Consumer Bank AG |
6 to 72 |
Not explicitly stated |
Zero-percent financing up to 12 months |
Consors Finanz |
10 to 60 |
From 9 euros |
Flexible terms, easy installment payments |
E-Bike-Finanzierungen |
Not precisely stated |
Flexibly selectable |
Monthly installment adaptable to budget |
You can choose the monthly installment to fit your income. Many providers do not require a down payment. This makes getting started especially easy.
Caution: Even if the installments are flexible, you should always keep an overview of your finances. Multiple financing agreements at the same time can quickly become confusing.
Disadvantages
Interest costs
When you buy an e-bike in installments, you often pay more than just the pure purchase price. Many financing offers include interest. Only with 0% financing does the price remain the same. However, these offers usually only apply to short terms. For longer terms or with certain retailers, interest is added. Interest increases the total cost of your e-bike.
Here you can see how different the interest costs can be:
Financing type |
Interest rate (nominal/effective) |
Term |
Purchase price (EUR) |
Interest costs (EUR) |
Monthly installment (EUR) |
|---|---|---|---|---|---|
Retailer financing (Fahrrad XXL) |
approx. 8% nominal |
12 months |
1,599.99 |
70.19 |
approx. 139.19 |
Bank loan (Smava average) |
approx. 4.71% effective |
12 months |
1,599.99 |
40.25 |
approx. 136.69 |
Bank loan (Smava average) |
approx. 4.71% effective |
24 months |
1,600 |
higher (not exact) |
69.92 |
0% financing (bike retailer) |
0% |
usually 10-12 months |
variable |
0 |
variable |
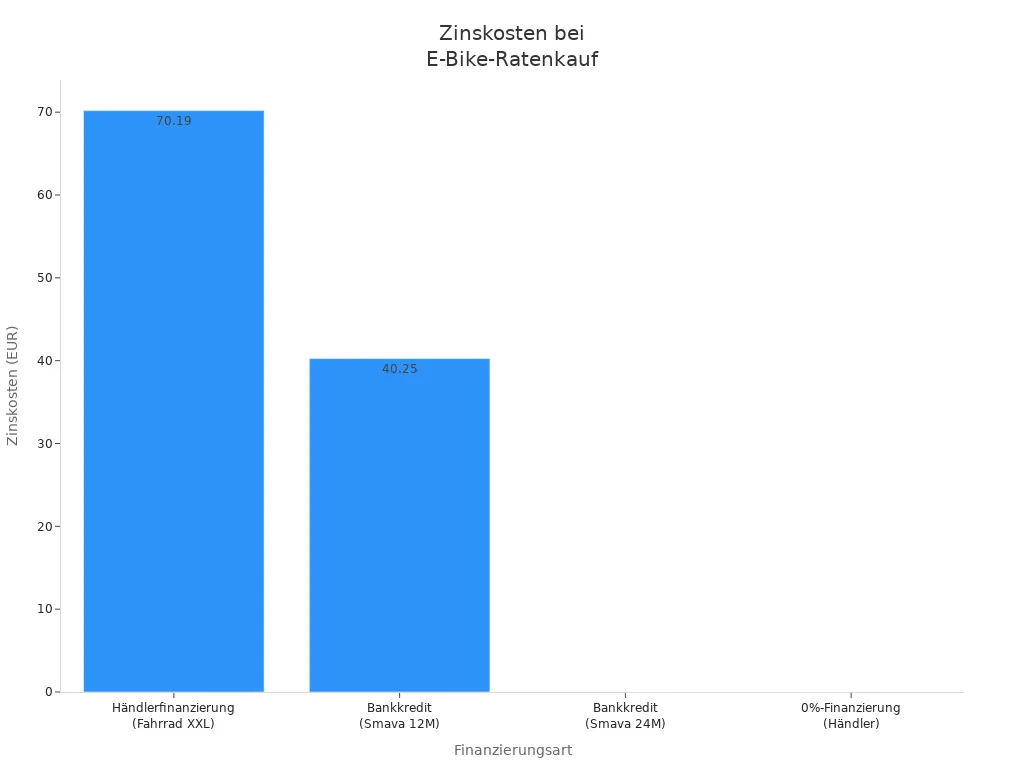
Tip: Always check the interest rate. A seemingly cheap offer can end up being expensive due to high interest rates.
Financial commitment
With an installment purchase, you enter into a long-term obligation. You must pay a fixed amount every month, often over several years. Many contracts run for 24 or even 60 months. This limits your financial freedom. You can make fewer spontaneous large expenditures during this time. If you suddenly have less money, for example due to job loss, the monthly installment can become a burden.
Many people underestimate how long they are tied to a contract. Financial commitment is one of the most common disadvantages of an e-bike in installments. Especially with leasing, you must note that the e-bike belongs to the provider during the term. You cannot simply sell or keep it if you want to end the contract.
Total costs are often higher than with a direct purchase.
The commitment usually lasts 2-3 years or longer.
You are bound by the contract terms and cannot freely use or sell the e-bike.
Note: Before signing, consider whether you can really pay the monthly installments over the entire term.
Credit check
Before you get an e-bike in installments, the retailer or the bank checks your creditworthiness. This means they check whether you have paid bills on time in the past and whether you earn enough money. If you have a negative SCHUFA entry or a low income, many banks will reject your application. The credit check is the most important prerequisite for financing.
Installment purchase without credit check |
|
|---|---|
Creditworthiness is checked based on SCHUFA and credit history |
No SCHUFA query, instead evaluation based on regular income or collateral |
Higher risk of rejection with poor credit rating |
Allows even people with lower credit ratings to purchase in installments |
If you don't have good credit, there are alternatives like private financing or online loans. However, these are often more expensive because interest rates are higher. Sometimes it helps if a second person signs as a guarantor.
Caution: Rejected financing can have a negative impact on your credit rating. It is best to check your credit score before applying.
Financing models
You have various options for financing your e-bike. Each option has its own advantages and disadvantages. Here is an overview of the most important models:
Retailer installment plan
With a retailer installment plan, you pay off your e-bike in fixed monthly installments. The term is usually between 12 and 48 months. The installments remain the same, which allows for good planning. Many retailers charge interest, often around 6%. You can use your e-bike immediately, but early termination is rarely possible. Total costs increase due to interest and fees.
Tip: Some retailers offer 0% financing. In that case, you pay no interest, but often have to choose a longer term.
Bank loan
With a bank loan, you are flexible in your choice of retailer. The bank checks your creditworthiness and sets the interest rate. This is usually between 4% and 6%, depending on your credit rating. You can adjust the term and sometimes make extraordinary repayments. A bank loan is suitable if you want to buy your e-bike independently of the retailer.
Note: Interest rates may be higher than with a retailer, but you are not bound to specific models.
Leasing
Leasing is particularly interesting for employees. You lease the e-bike through your employer, benefiting from tax advantages. Since 2019, with salary sacrifice, you only need to tax 0.25% of the gross new price as a non-cash benefit. If the employer covers the costs, the tax is eliminated entirely. You can use the e-bike privately and save up to 40% compared to purchasing it. Maintenance and insurance are often included.
However, note: You are tied to your employer. In case of illness, parental leave, or a job change, additional costs may arise. At the end of the term, you can purchase or return the e-bike. The acquisition may have tax implications.
Tip: Get advice before signing the contract to ensure you are aware of all obligations.
E-Bike Subscription
An e-bike subscription offers you maximum flexibility. You rent the e-bike for 3 to 18 months. The monthly costs are higher than with other models, but you do not enter into a long-term commitment. You do not acquire ownership, but you can test the e-bike extensively. A subscription is suitable if you only need the e-bike temporarily or want to try out different models.
Model |
Term |
Ownership |
Flexibility |
Costs |
Special Features |
|---|---|---|---|---|---|
Dealer installment purchase |
12-48 months |
Yes |
Low |
Interest approx. 6% |
Fixed installments |
Bank loan |
Flexible |
Yes |
Medium |
Interest 4-6% |
Free choice of dealer |
Leasing |
24-36 months |
No* |
Medium |
Tax savings |
Via employer, insurance incl. |
E-bike subscription |
3-18 months |
No |
High |
High |
Short term, no ownership |
*Ownership possible after the end of the term for an additional charge.
Dealers & Offers
Well-known Providers
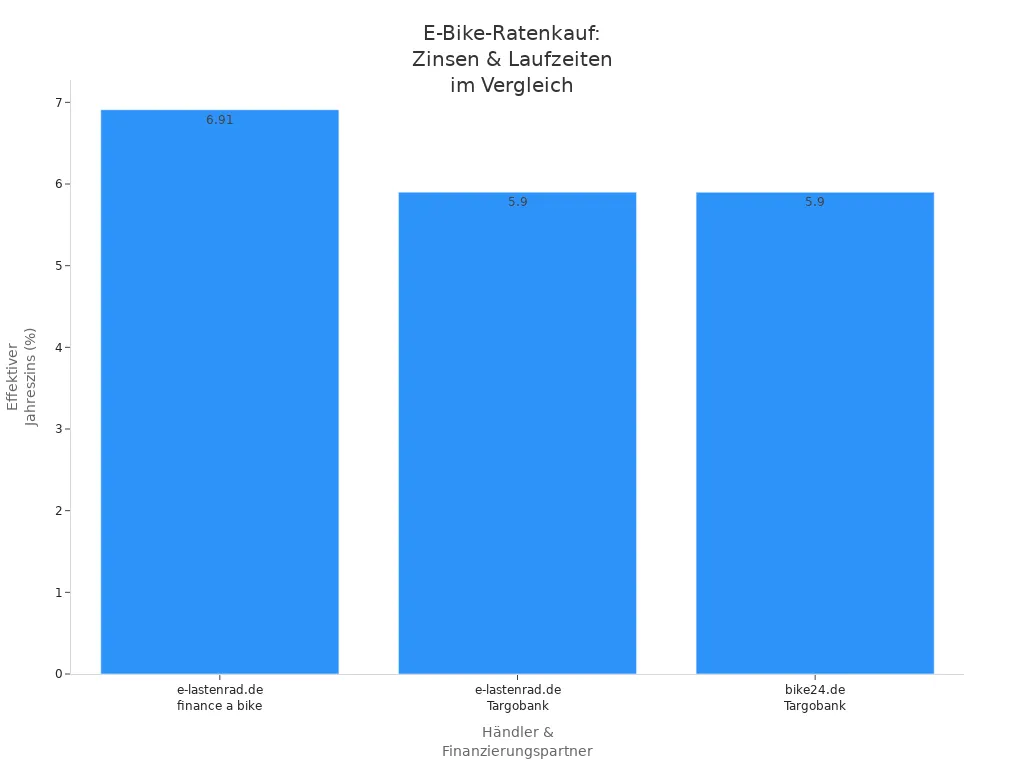
Many dealers in Germany offer you attractive options to buy an e-bike in installments. Here you will find an overview of well-known providers and their terms:
Dealer |
Financing Partner |
Term (Months) |
APR (%) |
Special Features |
|---|---|---|---|---|
bike24.de |
Targobank |
5.9 |
From €499, quick online application |
|
e-lastenrad.de |
finance a bike |
5.12 - 6.91 |
0% interest in the first 30 days, max. €6,000 loan |
|
e-lastenrad.de |
Targobank |
up to 60 |
3.9 (6-36), 5.9 (37-60) |
Up to €12,000 loan, longer terms possible |
E-BIKE ONLY |
Installment payment |
variable |
Flexible installment amount, first installment after delivery |
|
Creditplus/Klarna |
12 to 120 |
variable |
Low interest, high approval rate |
|
Targobank |
up to 60 |
variable |
Free shipping, buyer protection, free returns |
Tip: Use comparison portals like Verivox to find the best terms for your installment purchase.
Flexible Options
You can choose from many flexible payment methods today. In addition to classic bank transfer, dealers offer modern methods such as PayPal, Klarna, Amazon Pay, or Apple Pay. Installment and leasing models are particularly popular. Many dealers allow you to individually determine the term and the amount of the monthly installment. With easyCredit, for example, you can often pay the first installment after 30 days. Leasing offers you tax benefits and flexible contract options at the end of the term.
Financing via partner banks such as Targobank or Creditplus
easyCredit installment purchase: Flexible installments, no hidden costs
Leasing: Particularly attractive for employees
Tips for Selection
When choosing your dealer, look for transparent terms and flexible repayment periods. Check if 0% financing is possible. Many dealers offer this option for short terms. Compare the APRs and look out for hidden fees. Use comparison portals to find the best offers.
Note: The best time for affordable deals is in autumn and winter. In September and October, dealers clear their warehouses. Black Friday and Cyber Monday also often feature deep discounts. Prices usually rise in spring and summer.
If you want to buy an e-bike in installments, a detailed comparison is worth it. This way, you will find the best offer for your needs.
Practical Notes
Signing the Contract
Before you sign a contract, you should check the terms carefully. Many providers allow special repayments, i.e., additional payments to pay off the loan faster. This can help you save on interest costs. However, there are differences:
Description |
|
|---|---|
Free special repayment |
Some banks offer you free special repayments at any time. |
Limited amount |
Often you are only allowed to make special repayments of 5–10% of the loan amount per year. |
Limited number |
Some providers only allow a certain number of special repayments per year. |
Prepayment penalty |
A fee may apply for early repayment, usually 0.5–1% of the remaining debt. |
Contract dependence |
You can find the exact rules in the contract. Check these carefully before signing. |
Tip: Read the fine print. Pay attention to fees and check if you can flexibly make special repayments.
Search for Offers
You can often find the best deals at specialized online bicycle dealers. These dealers work with banks like Targobank and offer you individual installment solutions. Many shops offer secure payment through SSL encryption and buyer protection. You often benefit from free return shipping and fast delivery. Use filter functions on the websites to find suitable offers according to price, brand, or category. Good customer service and transparent terms help you discover the best offer.
Large selection of brands and models
Flexible installment options through financial partners
Secure and fast processing
Free return shipping and Click & Collect
Note: Always compare several offers and watch out for hidden costs.
Funding Opportunities
In Germany, there is no uniform state subsidy for installment purchases. Most grants are aimed at e-cargo bikes, often for commercial users. Some federal states and municipalities offer their own programs, sometimes for private individuals. These grants reduce the purchase price and thus facilitate financing. Under certain conditions, health insurance companies can provide a subsidy if the e-bike is considered a medical aid. The subsidy conditions vary by region:
Special features |
|
|---|---|
Federal states |
Some support private users, others only commercial. Lower Saxony supports exclusively private individuals. |
Municipalities |
Many cities offer their own premiums, often with special conditions such as proof of green electricity. |
Federal level |
Funding usually only for commercial users, up to €2,500 subsidy for e-cargo bikes. |
Other |
Social grants possible for low-income families. |
Tip: Inquire with your city or federal state about current subsidy programs.
You have many options for buying an e-bike in installments. The advantages: You remain flexible, use the bike immediately, and adjust the installments to your budget. You should consider disadvantages such as interest and long-term commitments.
Choose dealer installment purchase if you want fast processing.
-
Choose leasing if you are looking for tax benefits.
Tip: Always compare offers and check what suits you best. This way, you can fulfill your dream of an e-bike even with little money! 🚲
FAQ
How does installment purchase work for an e-bike?
You choose your e-bike, fill out the installment purchase form, and sign the contract. Then you pay a fixed amount monthly. The e-bike is yours immediately.
What documents do I need for an installment purchase?
You usually need:
A valid identity card
Proof of your income
Proof of your residence
Tip: Keep all documents digitally ready. This makes the application faster.
Can I pay off the e-bike early?
Yes, many dealers offer special repayments. You can pay off the e-bike faster and save on interest. Check the contract terms before deciding.
What happens if I cannot pay an installment?
If you contact the dealer or bank immediately, you can often find a solution together. If you miss several installments, late payment fees or a negative credit agency (SCHUFA) entry may occur.
Are there e-bikes available in installments without a credit check?
Some providers waive the SCHUFA check. However, you often have to pay higher interest rates or provide additional collateral. Compare the offers carefully.